

Let’s chat about the current state of inflation, interest rates, and bond yields in Canada.
Inflation has been decreasing into 2026.

Find more statistics at Statista
As of 2026, interest rates in Canada are also going down.
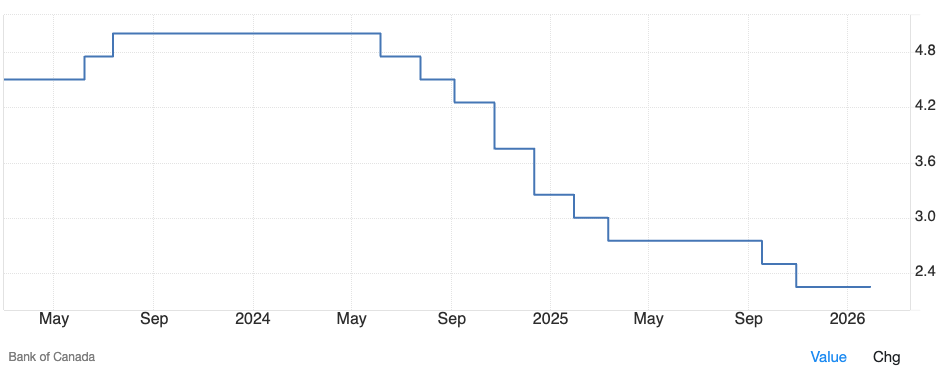
Let’s take a step back for a minute and answer the question: where do interest rates come from? And, by extension, bond yields, which impact your pension’s commuted value.
Interest rates come from three places:
- Inflation
- Risk
- Profit
Let’s say your friend comes to you and asks “can you lend me $1,000? I’m going to need it for three years”.
You say, “Okay, I’ll lend you that. But first of all, I want to make sure that when I get that $1,000 back, it will buy me $1,000 worth of goods. So I’m going to have to charge you something for inflation.”
That’s step number one.
Let’s pretend inflation stays at around 2%, which is the target here in North America. So in a simplistic world, two percent multiplied by three years is six. So you would say you need 6% on top of the $1000 you give your friend today.
Second, you need to factor in your risk. What if your friend fails to pay you back? So you should add a percentage in there for risk. Not a lot, but something.
Third, you start to consider all of the things you could go and buy yourself with that money to enjoy it rather than letting your friend borrow it. For example, you could use that $1000 to buy some clothes, buy your spouse something, or get something for your kids. So, in order to motivate you, you will want to add a percentage so you can make a little profit off the loan. In the world of business, the banks do this so they can make a profit because at the end of the day, they are a business and need to make a return on the money they lend out.
So for argument’s sake, let’s say you want 10% back over three years. There’s the interest rate. And the moral of the story is the cornerstone of interest rates is inflation. So when you see inflation go up, interest rates are going to go up.
Next, let’s talk about bond yields.
As a hypothetical example, let’s say “Bank A” and “Bank B” both want $5 billion for a project. Well, who would I rather lend money to? “Bank A” or “Bank B”? Say that you decide you would rather lend money to “Bank A” because you trust them more. This means “Bank B” is going to have to pay a little more to get your attention. The quality of the borrower comes into question.
Duration is the second factor. How long is the bond written for? In other words, how long does the bank want the money for? Three years? No, let’s say they have requested to have the money for 30 years. Wow, that’s a long time so we’re going to have to charge more because we don’t know what the environment is going to be like over the next 30 years. That’s called duration.
The third factor to consider is rising interest rates. As we discussed earlier in this post, they’re not going down any time soon and will continue to rise over the next few years. When interest rates are going up, people don’t want to buy long term bonds.
Lastly, what’s the impact of the bond yield on a commuted value? Well, imagine a teeter totter. If the bond yield goes up, your commuter value goes down. And vice versa.
What about copycat annuities? Insurance companies will write the copycat based on the commuted value number. If the interest rates go down (as they currently are), your commuted value goes up, which is great news for you!
If you have questions about inflation, interest rates, bond yields, your pension’s commuted value, or how copycat annuities work, let’s hop on a 15-minute Zoom call. Get a free consultation to analyze and discuss your pension options. Our services are at no cost to you. To book your call, click here.



