

Imagine your pension statement suddenly showing an extra $50,000–$100,000…without you working a single extra day. That’s what can happen when interest rates shift and your commuted value gets recalculated. The question is: do you cash out or stay put?
For anyone with a defined-benefit pension plan, the commuted value represents the present-day dollar amount of all future pension payments you’re entitled to receive. Instead of collecting a monthly pension for life, you take that value as a lump sum when you retire or leave your employer. This lump sum reflects what it would cost today to fund the lifetime pension your plan promises. Actuaries calculate it using assumptions such as life expectancy, inflation, and especially interest rates.
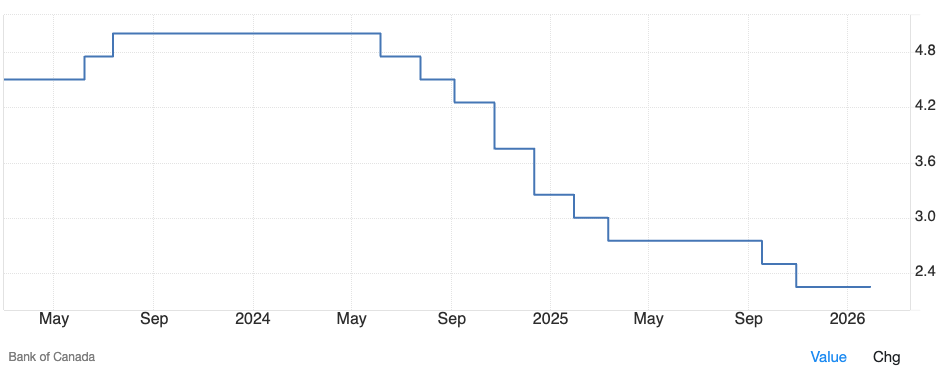
Why does that matter? Because the size of this lump sum can fluctuate based on market conditions.
That’s why understanding how commuted value works (and especially how interest rates affect it) is crucial. We could be talking bonus cash upwards of $25k, $50k or more!
How Interest Rates Affect the Commuted Value Calculation
Commuted value rises or falls based largely on interest rates.
When interest rates decline, commuted values increase. When interest rates rise, commuted values decrease. Think of it like a teeter-totter. As interest rates go down, the amount of money needed today to generate future payments goes up. Lower interest rates mean the discount rate applied to those future payments is lower, so the lump sum required to match the value of the pension increases.
A simple example makes this clear:
If your commuted value was estimated at $650,000 six months ago when interest rates were higher, a drop in rates today could push that number to $700,000 or more. This is not uncommon during periods when central banks signal that interest rates are trending downward.
Because of this direct relationship, changes in the broader economy can significantly increase what your pension is worth as a lump sum.
Comparing Commuted Value and a Copycat Annuity
When you leave your pension plan or retire, you typically choose between two options: taking the commuted value or choosing a lifetime pension through a copycat annuity.
Commuted Value (Lump Sum Pension)
Taking the commuted value gives you full control over the money. You can invest it, use it strategically for tax planning, or build an estate for your beneficiaries. A low-interest-rate environment often makes the lump sum option more attractive because the commuted value calculation becomes more generous.
However, taking the lump sum means taking on responsibility. Investment performance becomes your risk. If markets perform poorly or your investment strategy isn’t sound, you could deplete the funds more quickly. You also carry longevity risk — the possibility of outliving your savings.
Copycat Annuity (Guaranteed Monthly Pension)
A copycat annuity mimics the pension you would have received from your employer. It offers predictable monthly income for life without requiring you to manage investments or worry about market swings.
Here’s an important point: even if your commuted value goes up because interest rates dropped, the copycat annuity payment does not increase. An insurer pricing the annuity uses current interest rates, but they are simply offering you the pension as originally promised. Higher commuted value doesn’t equal higher monthly payouts. In some cases, there may be a cash surplus left over after the copycat annuity is purchased. This surplus often amounts to a few percentage points of the total value and is paid directly to you. While not guaranteed, it can be a nice added benefit.
Some retirees choose the annuity for simplicity and peace of mind. Others prefer the lump sum for flexibility. Neither option is automatically better, the right choice depends on your personal situation.
Timing Your Pension Decision
Timing plays a major role in whether it makes sense to take your commuted value.
Because commuted value increases when interest rates fall, retirees who happen to leave during low-rate periods can receive substantially larger lump sums. This was especially true in years like 2019 and 2020, when interest rates fell dramatically and commuted values soared.
If you are approaching retirement or considering taking your pension early, watching interest rate trends can be beneficial. A downward shift in long-term yields can quickly increase your commuted value.
That said, no one can perfectly time interest rates. Waiting for rates to fall even further can be risky if they unexpectedly rise or if plan rules change. Decisions should be guided by your personal financial situation rather than speculation.
Making the Right Pension Choice
To choose confidently between commuted value and a copycat annuity, follow a structured approach:
Evaluate your risk tolerance.
Clarify your retirement goals.
Review your full financial picture.
Understand tax implications.
Seek guidance from a pension specialist or financial advisor.
With careful planning and the right information, you can choose the pension option that gives you clarity, confidence, and the retirement outcome you want.
Book a free consultation call with an advisor at Pension Solutions Canada by clicking here.



